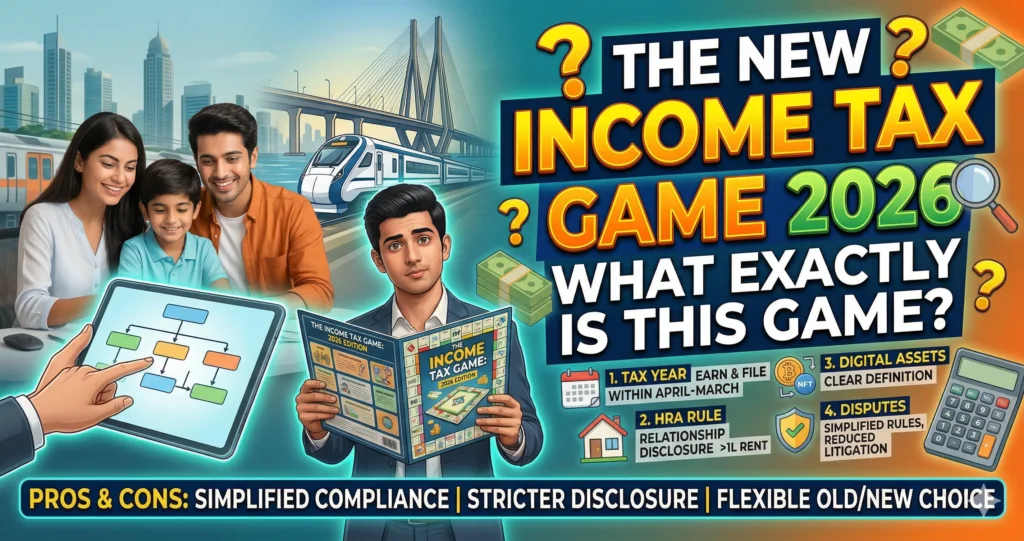
Following the 2025 Budget and the enactment of the New Income Tax Act 2025, Income Tax is no longer merely a matter of asking, “Should I file a return or not?” It has now literally evolved into a game—and *you* are the player.
This game consists of two levels:
- Level 1: How much tax to pay (new slabs, rebates, regimes, etc.)
- Level 2: Tracking every single penny of yours—specifically, what information is being recorded in the government’s database.
In today’s blog, we will be focusing on Level 2: “What exactly is the government tracking now?”
Level 1 Quick Guide: New Tax Slabs and Rebates 2025–26
Let’s briefly understand the context, as this is where the rulebook of the game begins.
- The *New Regime* is the default option; if you wish to opt for the *Old Regime*, you must specifically declare it (for individuals without business income, this choice can be changed on a year-to-year basis).
- The basic exemption limit has been raised to ₹4 Lakhs—meaning there is no tax liability up to this income level (under the New Regime).
- Tax Slabs (New Regime, FY 2025–26 / AY 2026–27 – Provisional):
- 0 – 4,00,000: 0%
- 4,00,001 – 8,00,000: 5%
- 8,00,001 – 12,00,000: 10%
- 12,00,001 – 16,00,000: 15%
- 16,00,001 – 20,00,000: 20%
- 20,00,001 – 24,00,000: 25%
- Above 24,00,000: 30%
- Thanks to the rebate, the actual tax liability can effectively become zero for income levels up to approximately ₹12 Lakhs (excluding income subject to special rates, such as Capital Gains or Gaming Income).
This all sounds great, but there is a twist to the game—once transactions exceed this “free limit,” a permanent digital footprint of those activities is recorded within the system.
Level 2: AIS / TIS – The Income Tax Department’s “CCTV” Watching Your Every Move
The most significant change introduced recently is the Annual Information Statement (AIS) and the Taxpayer Information Summary (TIS).
What is AIS?
- The AIS is a comprehensive report of all your major financial transactions throughout a financial year—covering everything from bank accounts, Demat accounts, and credit cards to TDS, TCS, interest income, dividends, and property deals.
- Previously, Form 26AS was limited primarily to TDS and TCS details; now, all other financial details are consolidated within the AIS.
- You can access and download this statement directly by logging into the e-filing portal and navigating to “Services → AIS.”
What is TIS?
- The TIS serves as a summary of the information contained within the AIS—much like the “Stats Screen” in a video game: it displays your total income, capital gains, interest earnings, and so on. In short, it provides a snapshot of exactly how much the Income Tax Department believes you have earned.
What has been added starting from the 2025–26 financial year?
The scope of transactions covered under the AIS has been expanded to include:
- Insurance commissions and maturity proceeds
- Transactions involving Cryptocurrencies or Virtual Digital Assets
- Income earned from freelancing or “Gig” work
- Even minor interest entries (such as those from Fixed Deposits or Savings Accounts)
This means that the mindset—”Who is going to notice these small interest earnings?”—is now 100% outdated.
What Exactly Does the Government Track? – 16 “Mega Moves” (High-Value Transactions)
Now, for the most crucial section of this entire process: which transactions are automatically reported to the Income Tax Department? This is primarily based on the “SFT – Specified Financial Transactions” list and recent regulatory expansions.
All the thresholds listed below are calculated on an “aggregate annual” basis—meaning that even if you cross the prescribed limit across two or three separate transactions, a report will still be generated.
1) Cash Deposits/Withdrawals in Bank Accounts
- Cash deposits or withdrawals totaling ₹50 Lakhs or more in a *Current Account* within a single financial year.
- Cash deposits or withdrawals totaling ₹10 Lakhs or more in a *Savings Account* or any other type of account.
2) Credit Card Payments
- If a payment of ₹1 Lakh or more is made using *cash*.
- If payments totaling ₹10 Lakhs or more are made using any *other mode* (such as NEFT, UPI, or Direct Debit) over the course of the entire financial year, a report is generated.
3) Fixed Deposits / Bonds / Shares / Mutual Funds
- Investments totaling ₹10 Lakhs or more in Fixed Deposits (FDs), Bonds, or Debentures (calculated as an aggregate for the year).
- Transactions involving the purchase or sale of Shares and Mutual Funds—particularly those involving large amounts—fall under the SFT category and appear in your Annual Information Statement (AIS).
4) Property Purchase/Sale
- The purchase or sale of property valued at ₹30 Lakhs or more (whichever is higher: the Stamp Duty Value or the actual Transaction Value).
- These transactions are reported directly to the Income Tax Department by the respective Registrar or Sub-Registrar offices.
5) Foreign Currency / Travel / Forex Cards
- Purchase or expenditure of foreign currency (Forex) totaling ₹10 Lakhs or more, whether for overseas travel or for any other purpose.
- Annual expenditure totaling ₹10 Lakhs or more in foreign currency made through the use of Debit or Credit Cards.
6) Large UPI / Online Payments and Other High-Value Transactions
- SFT (Statement of Financial Transactions) reporting may apply to specific high-value purchases (e.g., jewelry, luxury goods) exceeding ₹2 lakhs; such transactions are subsequently recorded in the AIS (Annual Information Statement).
- Online gaming and capital gains are separately highlighted as “Special Rate Income,” and cross-verification is conducted to ensure they are duly accounted for.
By aggregating all this data, the Income Tax Department’s algorithm essentially checks: “Do the income you have declared and your actual expenses/investments align?”
Game Mechanics: ITR vs. AIS Mismatch = Notice
Now for the next part of the game—what happens if there is a discrepancy between what you’ve declared in your ITR and what appears in your AIS/TIS?
Some Key Sections:
- Section 139(9): Defective Return – A formal notification indicating that your tax return is technically flawed.
- Section 143(1)(a): Proposed Adjustment – The CPC (Centralized Processing Centre) proposes modifications to your return—such as adding additional income, reducing deductions, etc.
- Section 148: Income Escaping Assessment – The Department suspects that you have concealed income.
Penalty Levels (The Final Trap):
- A penalty ranging from 50% to 200% may be levied on under-reported or mis-reported income (depending on the specific section and case details).
- In cases of serious tax evasion (where the evaded tax exceeds ₹25 lakhs), there is a provision for imprisonment ranging from 6 months to 7 years.
In short—if you lose this game, you don’t just get a “Retry” option; sometimes, you face a definitive “Game Over + Penalty.”
“I’m a small taxpayer; who’s going to pay attention to me?” – This is a myth.
In the past, the attitude of “just deal in cash—nothing will happen” might have worked; however, thanks to today’s data-centric systems, even the ‘little guy’ is now under full surveillance.
Examples:
- Even minor interest credits in your savings account appear in your AIS (Annual Information Statement).
- UPI-based businesses, freelance earnings, and income from YouTube/AdSense/brand deals—all of these are traceable through payment gateways and banks.
- High-value or structured transaction data can also be reported by crypto exchanges, making it extremely difficult to conceal your VDA (Virtual Digital Asset) income.
The government’s approach is clear: provide relief by lowering tax slabs, but track 100% of the data.
If You Want to Win This Game – Practical Tips
1) Download and Check Your AIS Every Year
- Visit the e-filing portal to download your AIS (Annual Information Statement) in PDF or JSON format, and cross-check details regarding interest, dividends, TDS, and SFT transactions.
- If you spot any discrepancies, utilize the “Feedback” option within the AIS interface—you can attempt to correct the record by citing reasons such as “Not my transaction,” “Wrong value,” or “Duplicate.”
2) Understand Your Footprint—Both Cash and Digital
- Plan your large cash deposits and withdrawals strategically—for instance, keep in mind the prescribed limits of ₹50 lakhs for Current Accounts and ₹10 lakhs for Savings Accounts.
- When making substantial card payments (exceeding ₹10 lakhs), ensure that the corresponding income has been accurately declared in your tax filings.
3) If You Are a Freelancer or Business Owner
- Prepare a simple P&L (Profit & Loss) statement based on your UPI transactions, payment gateway records, and bank statements.
- Maintain consistency across your GST filings, business turnover figures, and the income declared in your ITR (Income Tax Return)—any mismatch in these figures currently serves as a major red flag for tax authorities.
4) “No Tax Liability” Does Not Mean “No Return Filing”
- Even if your tax liability is zero (e.g., your income is below ₹12 lakhs, and tax is fully offset by rebates), filing an Income Tax Return may still be mandatory if your total income exceeds ₹4 lakhs.
- Furthermore, if you have earned “special income” (such as Capital Gains, earnings from online gaming, etc.), filing an Income Tax Return becomes compulsory.
The Game Strategy: Not “Tax Planning,” but “Data Planning”
Beyond 2026, Income Tax is no longer merely a game of deductions and sections like 80C or 80D; the game now revolves around data.
The Strategy in Brief:
- First comes income planning, then tax planning—and, even before that, data footprint planning.
- Track the volume of transactions across different banks, identify which accounts handle high-value transactions, and view everything—including card usage, UPI, crypto, and property holdings—as part of one comprehensive, overall picture.
- Every year, before filing your ITR, review your AIS and TIS statements and ask yourself just one question: “The money I am spending or investing—where am I declaring it as income?”
Final Level: “Transparent Player = Safe Player”
There are no cheat codes in this game—only two options:
- Transparent Player: Provide matching data for everything you earn, file your returns on time, check your AIS, and relax.
- Risky Player: Adopt the “Who’s going to find out?” attitude, ignore your AIS, and get ready for new “levels” involving notices, penalties, and inquiries.
The government is currently offering you tax concessions through slabs, but it is simultaneously tracking your data comprehensively—this is the true plot of “The New Income Tax – Game 2026.”
