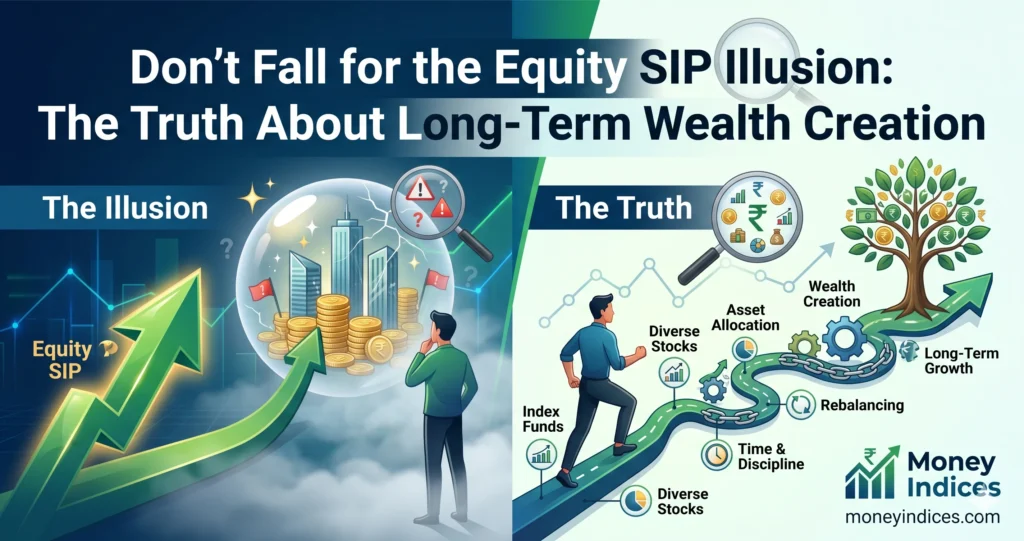
Investing through SIPs (Systematic Investment Plans) has become one of the most popular ways for Indians to build wealth. From YouTube videos to financial advisors, everyone talks about SIPs as a “guaranteed” path to long-term returns.
But here’s the uncomfortable truth — many investors misunderstand how SIPs actually work.
This misunderstanding leads to poor decisions like early exits, chasing past performance, and expecting unrealistic returns. In reality, SIPs are powerful but only if used correctly.
In this blog, we’ll break down the real story behind SIP investing, backed by data, experience, and practical insights.
The Biggest Myth: SIPs Always Deliver 12% Returns
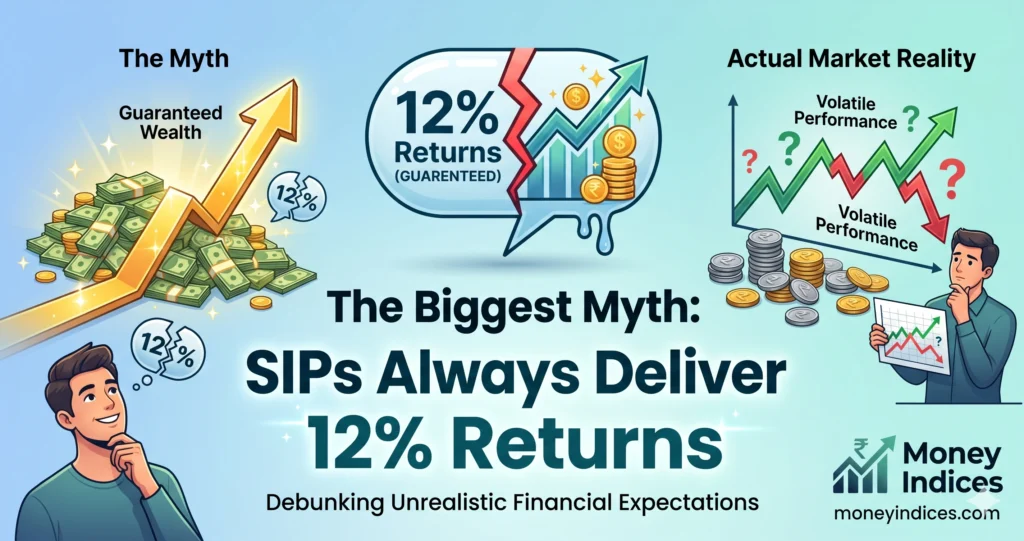
One of the most common assumptions is that SIPs consistently deliver 12% returns every year.
This belief is everywhere — retirement calculators, financial planners, and even social media influencers often use this number as a standard benchmark.
However, real market data tells a different story.
Returns are not fixed. They fluctuate depending on:
- Market cycles
- Entry and exit timing
- Investment duration
- Fund selection
In fact, over different time periods, SIP returns can vary widely — sometimes even below expectations.
👉 Reality check: SIPs don’t guarantee returns. They average out volatility over time.
Why Missing the Best Days Can Destroy Returns
One of the most powerful insights from market data is this:
A small number of “best days” contribute a large portion of long-term returns.
If you miss those days, your returns drop significantly.
For example:
- Staying fully invested → ~15%+ returns
- Missing just 10 best days → returns drop sharply
- Missing 30–50 best days → returns can fall dramatically
What does this mean?
Markets often recover sharply after crashes. Investors who exit during panic:
- Miss the rebound
- Lock in losses
- Lose compounding benefits
👉 Lesson: Timing the market is extremely difficult — staying invested is far more important.
The Real Power of Time in SIP Investing, Equity SIP Illusion
Time is the single biggest factor in wealth creation.
Data shows:
- Over 7-year periods, equities delivered 10%+ returns ~84% of the time
- Over 10–11 years, investments often tripled
- Over 12–13 years, investments frequently multiplied 4 times
Why does this happen?
Because of compounding.
When you stay invested:
- Returns generate more returns
- Market volatility smooths out
- Wealth grows exponentially
👉 Key Insight: SIP is not about timing the market — it’s about time in the market.
The Silent Killer: Early Exits
One of the biggest mistakes investors make is exiting too early.
Data reveals:
- A large number of investors exit within 2 years
- Many panic during market crashes
- They miss the recovery phase
Example: COVID Market Crash
During early 2020:
- Markets fell sharply
- Many investors exited out of fear
But what happened next?
- Markets rebounded strongly
- Those who stayed invested gained significantly
👉 Investors who exited:
- Missed the rally
- Lost long-term wealth potential
Why Investors Fail Despite Choosing Good Funds
Even when investors pick good mutual funds, they often fail to achieve good returns.
Why? Because of behavior.
Common Mistakes:
- Panic selling during downturns
- Chasing last year’s top-performing funds
- Stopping SIPs during market falls
- Expecting quick profits
👉 Investing success is less about picking the best fund — and more about discipline and patience.
The Power of Step-Up SIP (Game Changer)
A simple but powerful strategy many investors ignore is Step-Up SIP.
What is it?
Increasing your SIP amount every year as your income grows.
Example:
- ₹10,000/month for 20 years at 12% → ~₹92 lakh
- Increasing SIP by 10% yearly → ~₹1.86 crore
That’s more than double the wealth — just by increasing contributions.
👉 Lesson: Wealth grows faster when you invest more over time, not just stay invested.
Market Volatility Is Normal (And Necessary)
Many investors fear market volatility. But volatility is not the enemy — it’s part of the process.
Markets go through cycles:
- Bull phases (growth)
- Bear phases (decline)
Interestingly:
The best market days often come immediately after the worst days.
So if you exit during a fall, you’re likely to miss the recovery.
👉 Smart investors don’t avoid volatility — they use it to their advantage.
The Danger of Chasing “Last Year’s Winners”
Another major mistake is performance chasing.
Many investors:
- Look at last year’s top-performing funds
- Invest based on recent returns
- Switch frequently
Why this fails:
- Top-performing funds often slow down later
- Market leadership keeps changing
- You end up buying high and selling low
👉 Better approach:
Choose funds based on:
- Consistency
- Risk management
- Long-term track record
SIP Is Not Magic — It Needs Discipline
SIPs are often marketed as a “set and forget” strategy.
While automation helps, it doesn’t eliminate the need for discipline.
To succeed with SIPs, you must:
- Stay invested during downturns
- Avoid emotional decisions
- Increase contributions over time
- Align investments with goals
👉 SIP works best when combined with behavioral discipline.
Practical Strategy for Smart SIP Investors
Here’s a simple framework you can follow:
1. Think Long-Term (Minimum 7–10 Years)
Short-term investing increases risk and reduces returns.
2. Don’t Stop SIPs During Market Falls
Falling markets = buying opportunities.
3. Use Step-Up Strategy
Increase SIP annually by 5–10%.
4. Avoid Checking Portfolio Daily
Frequent monitoring leads to emotional decisions.
5. Stay Consistent
Consistency beats timing — always.
Expert Insight
From a practical investment experience standpoint, the biggest difference between successful and unsuccessful investors is not knowledge — it’s behavior.
Investors who:
- Stay patient
- Ignore noise
- Focus on long-term goals
…are the ones who build real wealth.
On the other hand, those who:
- React emotionally
- Try to time the market
- Chase trends
…often underperform, even with good funds.
👉 Conclusion from experience:
SIPs are powerful — but only when paired with discipline, patience, and realistic expectations.
SIP investing is not a shortcut to guaranteed wealth.
It is a long-term discipline-driven strategy that rewards patience and consistency.
The biggest myths you should avoid:
- SIPs always give 12% returns ❌
- You can time the market ❌
- Exiting during downturns is safe ❌
The truths you should follow:
- Stay invested ✔️
- Increase contributions ✔️
- Think long-term ✔️
👉 Remember:
Time in the market beats timing the market — every single time.
FAQs
1. Do SIPs guarantee returns?
No, SIPs do not guarantee returns. They help average out market volatility but returns depend on market performance.
2. What is the ideal duration for SIP investment?
A minimum of 7–10 years is recommended to benefit from compounding and reduce risk.
3. Should I stop SIP during a market crash?
Continuing a SIP during a crash buys units at lower prices, which can help long-term averages; the decision depends on your goals and situation.
4. What is a Step-Up SIP?
A Step-Up SIP is when you increase your investment amount periodically (usually yearly) to match income growth.
5. Why do investors lose money in SIPs?
Mostly due to behavioral mistakes like panic selling, early exits, and chasing performance.
6. Can I withdraw SIP anytime?
Yes, SIP investments (in open-ended funds) are flexible and can be withdrawn anytime, though long-term holding is recommended.
7. Is 12% return realistic for SIP?
It is not guaranteed. Returns can vary significantly, and past returns do not indicate future returns.
8. How important is consistency in SIP?
Consistency is the most important factor. Regular investing helps build wealth through compounding.
Mutual fund investments are subject to market risks, read all scheme related documents carefully.
