How to Start Investing in Your 20s
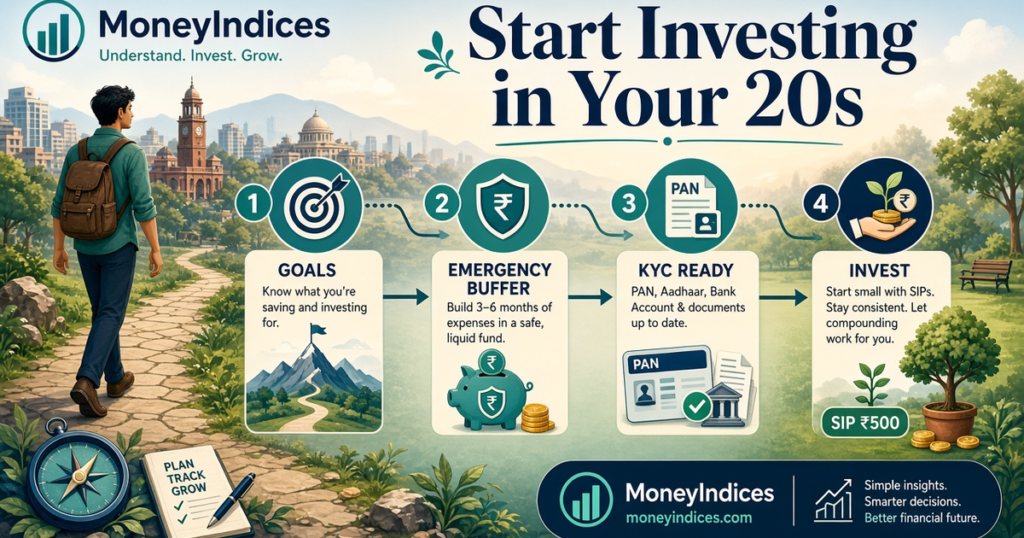
Starting to invest in your 20s in India usually means five practical steps: clear short-term cash needs and debts you cannot ignore; build a basic emergency buffer; complete KYC; pick simple regulated products that match your time horizon and risk capacity; and invest regularly while learning.
Time in the market and compounding matter, but returns are not guaranteed — and early investing does not remove the need to understand risk. This article is educational. It is not a recommendation to buy any specific security, fund, or crypto asset.
Why are your 20s a useful decade to learn investing?
Opinion / educational framing: Many people in their 20s have fewer dependents and a longer runway before large goals (home down payment, family costs, retirement). That longer horizon can make market volatility more tolerable for money earmarked for long-term goals — but only if you will not be forced to sell at a loss.
AMFI’s SIP education material illustrates that starting earlier can leave more time for compounding in hypothetical examples (illustrative rates, not forecasts). See AMFI SIP page. Historical or hypothetical growth ≠ future results. For instalment mechanics and compounding illustrations, see the What Is a Mutual Fund SIP and How Does It Work in India? guide.
Step 0: Separate “investing” from “surviving”
Before market products, map cash flows:
- Take-home salary / income after statutory deductions.
- Non-negotiable costs: rent, food, commute, EMIs, family support.
- High-interest consumer debt: clearing costly revolving credit usually beats “investing” the same rupees (general personal-finance logic; not tax or credit advice).
- Insurance gaps: term life / health coverage needs are personal; evaluate separately from investment returns.
If income is irregular (freelance, gig), keep a larger cash buffer before equity-heavy products. For paycheck mapping, automate-on-payday, and leak-cutting depth, see How to Save Money from Your Salary in 2026.
Step 1: Build a basic emergency buffer (short)
Opinion / practical standard: Park roughly 3–6 months of essential expenses in liquid form you understand. Exact months depend on job stability and dependents. Do not park the whole buffer in long-lock products.
Liquidity risk is real — SEBI lists it among key investing risks: SEBI Investor: Key risks.
For more detail: see the salary-saving guide for paycheck systems; for sizing and liquidity mistakes, see Avoid these mistakes while creating an emergency fund.
Step 2: How do you write goals in plain language?
SEBI’s asset-class guidance says choice depends on goals, risk tolerance, horizon, and overall financial situation. See SEBI Investor: Asset Classes.
Example goal framing (illustrative):
| Goal | Horizon | Typical risk discussion |
|---|---|---|
| Phone / travel next year | < 12 months | Capital protection usually prioritised over growth |
| Skills course in 2–3 years | Medium | Mix may be considered; depends on certainty of need date |
| Retirement / long-term wealth | 10+ years | Higher equity allocation may be considered by some investors |
This table is not a prescribed allocation.
Step 3: What risks should you understand before products?
SEBI highlights market risk, inflation risk, liquidity risk, business risk, volatility risk, and currency risk — SEBI key risks page above.
Inflation risk matters in your 20s: money sitting idle can lose purchasing power even if the rupee balance looks stable.
Editorial caution: “High return” marketing without risk disclosure is a red flag. Avoid borrowed money for speculative trading.
Step 4: What building blocks are available in India?
Bank and small-savings style instruments
Useful for short horizons and emergency cash (features and rates change — verify on bank / India Post / DFS notifications). Do not invent “best rate” claims here.
Mutual funds (summary)
A mutual fund pools investor money under a SEBI-regulated trust (sponsor, trustees, AMC, custodian) and issues units. Beginners often use diversified categories after KYC — a common process path, not a personal recommendation. Full structure / NAV / categories: What Is a Mutual Fund and How Does It Work?. Primary: SEBI Understanding Mutual Funds.
SIP (summary)
SIP is a mode of investing a fixed amount at regular intervals into a mutual fund scheme — not a separate fund type. AMFI notes instalments can be as little as ₹500/month (scheme-dependent). Full mechanics (rupee-cost averaging, cut-off NAV, myths): What Is a Mutual Fund SIP and How Does It Work in India?. See AMFI SIP.
Shares (direct equities)
Buying shares means part-ownership; prices can rise or fall. See SEBI How to Invest. Direct stock picking needs research bandwidth; many beginners use funds/ETFs first while learning.
ETFs
Exchange-traded funds provide diversified/index-like exposure and trade on exchanges; prices fluctuate — SEBI how-to / asset-class pages.
NPS (retirement-oriented)
National Pension System is a separate regulated retirement product with its own contribution and withdrawal rules. Tax treatment depends on regime and sections in force for your assessment year — verify on Income Tax Department / PFRDA materials before acting.
Crypto / VDAs (caution)
Crypto / virtual digital assets are not a starter default for most beginners — different risk, tax, and investor-protection profile than SEBI-regulated securities. Educational comparison: the Stock Market vs Crypto in India: Educational Comparison.
Step 5: How do you complete KYC and open clean rails?
Typical rails for a 20s investor in India:
- PAN and bank account in your name
- KYC for mutual funds / securities intermediaries (KRA ecosystem)
- Optional: demat + trading account if you want equities/ETFs
- Nomination on investments
Prefer regulated intermediaries. For mutual fund distribution, AMFI registration (ARN) and NISM certification requirements apply to distributors — process standard widely stated by AMFI investor materials; verify current AMFI “how to invest” pages.
Step 6: Why prefer systems over heroics?
Practical habits (opinion):
- Automate a SIP after salary credit if cash flow allows (setup details → What Is a Mutual Fund SIP and How Does It Work in India?)
- Increase investment amount when income rises (step-up thinking)
- Review yearly: goals, emergency fund, asset mix — not daily NAV anxiety
- Keep costs visible (direct vs regular plans). SEBI explains direct plans generally have lower expense ratios because there is no distributor commission in the plan structure. See SEBI regular vs direct
(For compounding and illustrative SIP math, see the What Is a Mutual Fund SIP and How Does It Work in India?; this page stays a roadmap.)
Step 7: Tax awareness without tax theatre
CONFIRMED for Assessment Year 2026–27 (old-regime framing on the Income Tax e-filing help): the Income Tax Department’s individual return-applicable help lists a combined ceiling of ₹1,50,000 under Sections 80C / 80CCC / 80CCD(1) and an additional ₹50,000 under 80CCD(1B) (NPS), where eligible — see Income Tax e-filing help — return applicable (individual). Availability still depends on regime choice and the law for your year. Do not invest only for a deduction if the lock-in or risk does not fit the goal.
Act transition note (as of 24 Sep 2026): The Income-tax Act, 2025 is in force from 1 April 2026 (CBDT). Section numbers can differ by tax year (for example, the familiar 80C-style basket is discussed as Section 123 under the 2025 Act for Tax Year 2026–27, while AY 2026–27 e-filing help still documents 80C / 80CCD(1B) under the 1961 Act). Keep verifying regime rules and limits on Income Tax Department resources for your year — do not treat any ceiling in this article as locked forever.
What mistakes are common in your 20s?
- Investing before an emergency buffer
- Copying a friend’s portfolio on social media
- Using leverage/F&O without understanding loss magnification
- Chasing “guaranteed high returns” (often a fraud signal)
- Ignoring expense ratios and exit loads
- Stopping SIPs only because markets fell (behaviour risk)
- Putting rent money into volatile assets
A simple 90-day learning plan (process)
Days 1–30: Track expenses; build/confirm emergency buffer; finish KYC. Days 31–60: Read SEBI investor pages on asset classes and mutual funds; shortlist categories (structure depth → What Is a Mutual Fund and How Does It Work?). Days 61–90: Start a small automated investment you understand; write a one-page investment policy for yourself (goals, horizon, what you will not buy).
FAQ
How much should I invest from my first salary?
There is no universal percentage. A common educational heuristic is “pay yourself first” after essentials and debt priorities — for example, starting with any sustainable amount and increasing later. Personalised percentages need your full budget — see salary guide for paycheck discipline.
Should I buy stocks or mutual funds first?
SEBI notes mutual funds suit investors who prefer professional management and diversification, while shares offer ownership with company-specific and market risk. Many beginners learn with diversified funds/ETFs first; that is a learning path, not a rule. For MF structure, see What Is a Mutual Fund and How Does It Work?.
Is SIP safer than lump sum?
SIP can reduce timing stress via rupee-cost averaging, but AMFI states it does not assure profit or protect against losses in falling markets. For the full comparison, see What Is a Mutual Fund SIP and How Does It Work in India?.
Can I invest if I have a student loan EMI?
Possibly, after ensuring EMIs and essentials are covered and keeping liquidity. High-interest debt usually deserves priority. Case-by-case.
Do I need a large amount to start?
AMFI notes SIP instalments can be as little as ₹500 per month (scheme-dependent). See the AMFI SIP page and the What Is a Mutual Fund SIP and How Does It Work in India?.
What if markets crash right after I start?
Volatility is normal for equity-linked products. Forced selling turns paper declines into realised losses. Match horizon to product risk.
External sources
- SEBI Investor — Asset classes: https://investor.sebi.gov.in/investment-assetclasses.html
- SEBI Investor — Key risks: https://investor.sebi.gov.in/securities-risks_trade_derivatives.html
- SEBI Investor — Understanding mutual funds: https://investor.sebi.gov.in/understanding_mf.html
- SEBI Investor — How to invest / shares & funds: https://investor.sebi.gov.in/securities-howtoinvest.html
- SEBI Investor — Regular vs direct: https://investor.sebi.gov.in/regular_and_direct_mutual_funds.html
- AMFI SIP explainer (incl. compounding illustrations): https://www.amfiindia.com/investor/become-mf-distributor?zoneName=sip
- Income Tax Department — e-filing help AY 2026–27 (80C basket / 80CCD(1B)): https://www.incometax.gov.in/iec/foportal/help/individual/return-applicable-1
- Income Tax Department (portal hub): https://www.incometaxindia.gov.in/
Educational disclaimer: This article is for educational purposes only and is not personalised financial advice. Verify current rules and product documents before acting.
