Direct answer
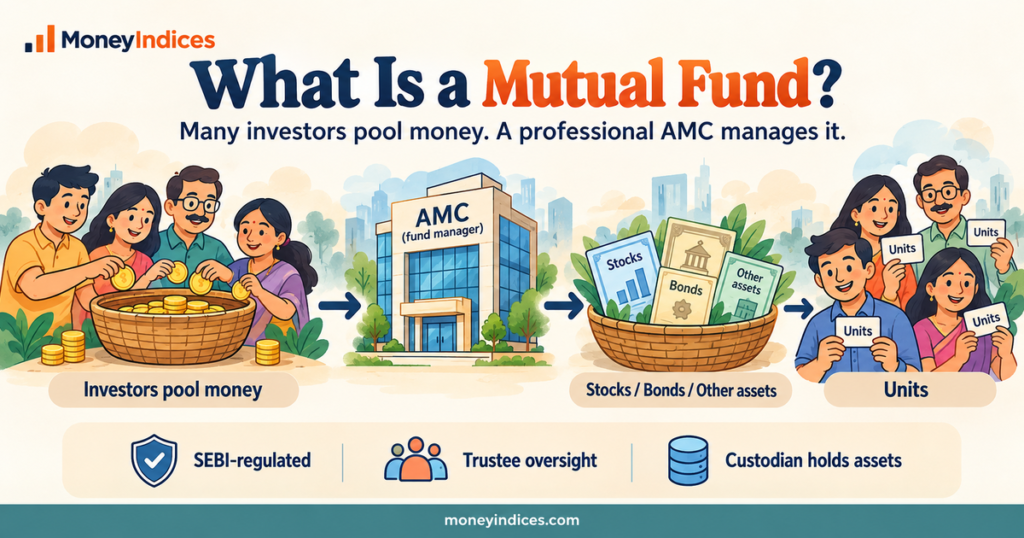
A mutual fund pools money from many investors, issues units, and invests that money in securities according to a disclosed scheme objective. In India, mutual funds are set up as trusts — with a sponsor, trustees, an Asset Management Company (AMC), and a custodian — and must be registered with the Securities and Exchange Board of India (SEBI) before collecting money from the public.
Under SEBI’s rules, a “mutual fund” is a fund set up as a trust and registered with SEBI (SEBI (Mutual Funds) Regulations, 2026; see also SEBI’s FAQs for Mutual Fund Investors, updated as on 31 Aug 2024). Your profit or loss is shared in proportion to your investment. Mutual funds are not risk-free and do not guarantee returns.
Educational only, not investment advice. Mutual fund investments are subject to market risks, read all scheme related documents carefully.
What exactly is a mutual fund?
According to SEBI, a mutual fund is a mechanism for pooling money by issuing units to investors and investing those funds in securities as disclosed in the offer document. Investors are called unitholders. Schemes may differ in objective (for example, equity-oriented vs debt-oriented), but the core idea is the same: one professionally managed pool instead of each investor buying every security alone.
SEBI’s investor education material describes mutual funds as a vehicle where you outsource research, selection, tracking, portfolio changes, and administration to an AMC, and receive an account statement summarising performance. See SEBI Investor: Understanding Mutual Funds.
Why do beginners often start with mutual funds?
Common reasons people start with mutual funds (educational framing, not advice):
- Diversification across many securities (subject to scheme rules)
- Professional portfolio management
- Regulated disclosures (objective, portfolio, NAV)
- Convenience of additional purchases and redemptions on business days
- Options such as Systematic Investment Plan (SIP) and Systematic Withdrawal Plan (SWP) — SIP is a mode of investing into a fund; see the short primer below and the full What Is a Mutual Fund SIP and How Does It Work in India? guide
SEBI lists advantages including professional management, expense caps under regulation, diversification mandates (with limited exceptions), transparency, convenience, and a strong regulatory framework — on the same investor education page.
How is a mutual fund structured in India?
According to SEBI FAQs, a mutual fund is set up as a trust with these roles:
| Role | What it does (plain English) |
|---|---|
| Sponsor | Like a promoter; establishes the fund |
| Trustees | Hold fund property for unitholders; supervise the AMC |
| AMC | Makes investment decisions in line with the scheme objective (SEBI-approved) |
| Custodian | Holds scheme securities in custody (SEBI-registered) |
SEBI’s Mutual Funds Regulations, 2026 (in force from 1 April 2026) require at least two-thirds of a trustee company’s board to be independent directors who are not associates of the sponsor, the AMC or the trustee company, and at least 50% of an AMC’s board to be directors who are not associates of the sponsor, its subsidiaries or the trustees.
This separation of roles is meant to protect investors; it does not remove market risk.
How does the money actually move?
- You complete KYC (Know Your Customer) and apply for a scheme (directly with the AMC or through an intermediary).
- You pay money (lump sum or SIP instalments).
- The fund allots units based on the applicable Net Asset Value (NAV).
- The AMC invests according to the scheme’s stated objective and asset allocation.
- NAV changes with the value of underlying holdings (and expenses/liabilities).
- You can redeem units (subject to exit load, lock-in if any, and settlement timelines stated in scheme documents).
What is NAV?
According to SEBI FAQs, NAV is the unit price of a scheme. It is determined by dividing net assets (total assets minus total liabilities) by outstanding units on a particular date. NAV indicates the price context for buying or redeeming units. For SIP-specific applicable-NAV / cut-off and funds-realisation timing, see the What Is a Mutual Fund SIP and How Does It Work in India?.
Illustration aligned to SEBI FAQ arithmetic (not a live scheme): SEBI’s worked example uses total assets ₹200 lakh minus liabilities ₹10 lakh (= net assets ₹190 lakh) ÷ 10 lakh units → NAV ₹19 per unit. Same formula: (total assets − total liabilities) ÷ outstanding units.
What categories do beginners usually hear about?
Names and risk profiles differ by scheme (for how SEBI’s equity categories differ, see Which Equity Fund Categories Do You Really Need?). Always read the Scheme Information Document (SID) and Key Information Memorandum (KIM). Broad educational buckets:
- Equity-oriented schemes: Higher market volatility; longer horizons are often discussed in investor education.
- Debt-oriented schemes: Interest-rate and credit risks still apply.
- Hybrid schemes: Mix of asset classes as per mandate.
- Index funds / ETFs: Track an index; ETFs also trade on exchanges. Framing from SEBI Investor: How to Invest and Asset Classes.
SEBI also explains regular vs direct plans: same portfolio, different cost because regular plans include intermediary distribution costs while direct plans do not. Lower expenses can improve net returns over time, all else equal — but that is a cost fact, not a performance guarantee. See SEBI Investor: Regular and Direct Mutual Funds.
SIP vs lump sum — short primer
- Lump sum: One-time investment into a scheme.
- SIP: Fixed amount at regular intervals (often monthly) — a mode of investing into a mutual fund, not a separate fund type.
Minimum SIP amounts vary by scheme and AMC; check the scheme’s SID/KIM. See the AMFI SIP explainer.
Full SIP explainer: What Is a Mutual Fund SIP and How Does It Work in India? (rupee-cost averaging, mandates, cut-off NAV, myths, stop vs redeem).
What should you read before investing?
SEBI’s investor reference sheet “Mutual Funds – Dos and Don’ts” asks investors to note, in the SID/KIM: investment objective, asset allocation, risk factors, performance vs benchmark (historical, not a promise), strategy, fund manager background, load structure, and how the scheme differs from others. The same sheet notes that past performance of a scheme is not indicative of its future performance. See SEBI: Mutual Funds – Dos and Don’ts (PDF).
Also track: Riskometer, expense ratio, exit load, tax treatment (depends on scheme type and holding period — verify with current tax law), and nomination.
What risks must you accept?
Mutual funds can lose value. Key securities-market risks SEBI lists include market/systematic risk, inflation risk, liquidity risk, business risk, volatility risk, and currency risk (where relevant). Diversification and asset allocation are risk-management ideas, not shields against loss. See SEBI Investor: Key risks.
Opinion / editorial: For most beginners, understanding how funds work and what can go wrong matters more than chasing last year’s top performer.
What does the process usually involve? (educational checklist, not advice)
Steps investor-education material commonly describes:
- KYC, completed once and recorded centrally through KYC Registration Agencies (KRAs) for the securities market.
- Writing down your own goal, horizon and risk capacity.
- Understanding scheme categories before looking at individual schemes.
- Comparing direct vs regular plan costs.
- If you use an intermediary, check their registration: an AMFI Registration Number (ARN) for mutual fund distributors, or SEBI registration for investment advisers.
- Matching the money invested to the horizon it can stay invested for.
- Keeping account statements and following NAV/portfolio disclosures.
FAQ
Are mutual funds guaranteed by SEBI or the government?
No. SEBI regulates and supervises mutual funds to protect investor interests; regulation is not a return guarantee (see SEBI mutual fund FAQs).
Is NAV the same as “returns”?
No. NAV is a unit price snapshot. Returns depend on change in NAV over your holding period, plus distributions if any, minus costs and taxes.
Can I lose money in a debt mutual fund?
Yes. Debt funds face interest-rate and credit risks; “debt” does not mean “safe like a bank deposit.”
What is the difference between AMC and mutual fund?
The mutual fund is the trust/scheme structure; the AMC is the investment manager appointed to run schemes under trustee oversight — SEBI FAQs.
Do I need a demat account?
Not always for mutual funds; many investments can be held in statement-of-account form with the AMC/RTA. Exchange-traded products like many ETFs typically need demat/trading setup. Check the product’s process.
Where do I complain if something goes wrong?
Use the mutual fund’s grievance channel first; unresolved issues can be escalated to SEBI through SCORES (https://scores.sebi.gov.in) or the SCORES mobile app.
External sources
- SEBI FAQs for Mutual Fund Investors (PDF, updated as on 31 Aug 2024): https://www.sebi.gov.in/sebi_data/faqfiles/sep-2024/1727242783639.pdf
- SEBI (Mutual Funds) Regulations, 2026 (in force 1 Apr 2026): https://www.sebi.gov.in/sebi_data/attachdocs/jul-2026/1783933012694.pdf
- SEBI — Mutual Funds: Dos and Don’ts (PDF): https://investor.sebi.gov.in/pdf/reference-material/MFunds.pdf
- SEBI SCORES (investor grievances): https://scores.sebi.gov.in
- SEBI Investor — Understanding Mutual Funds: https://investor.sebi.gov.in/understanding_mf.html
- SEBI Investor — How to Invest / securities types: https://investor.sebi.gov.in/securities-howtoinvest.html
- SEBI Investor — Regular vs Direct: https://investor.sebi.gov.in/regular_and_direct_mutual_funds.html
- SEBI Investor — Key risks: https://investor.sebi.gov.in/securities-risks_trade_derivatives.html
- AMFI SIP explainer: https://www.amfiindia.com/investor/become-mf-distributor?zoneName=sip
Disclaimer: This article is for educational purposes only and is not investment advice or a recommendation to buy, sell or hold any security or scheme. Mutual fund investments are subject to market risks, read all scheme related documents carefully. Verify current rules and scheme documents (SID/KIM) before acting.
